 Case 01
The home came first. The financing strategy came later.
Strong employment, meaningful savings, and a preapproval created confidence. But the buyers were already under contract before anyone compared how credit preparation, loan structure, and mortgage insurance could affect the long-term cost.
The order of decisions
Find an agent
Get preapproved
Sign contract
Build the financing strategy
$475KBase mortgage
0.625%Illustrative rate spread
$24.7KIllustrative five-year cost range
Explore the case
What happened
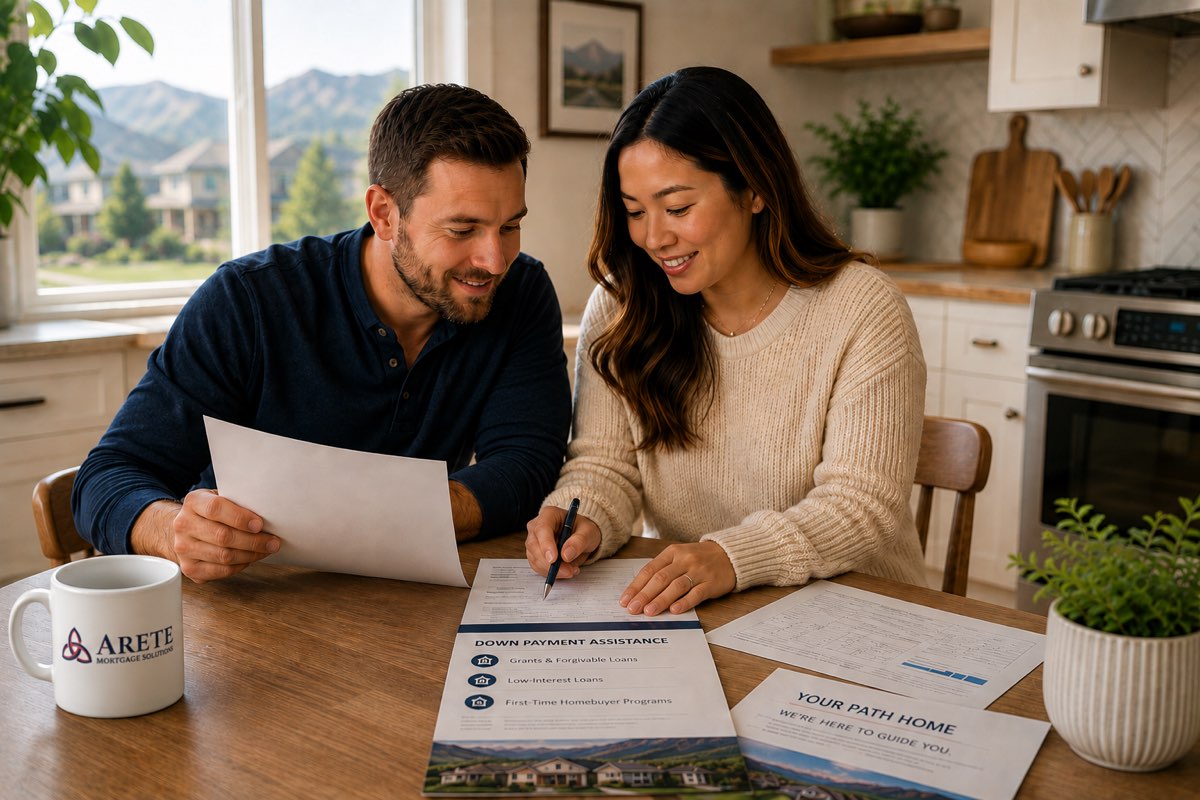
A Colorado Gen Z couple entered the market with approximately $50,000 in savings and a preapproval. Their credit scores were below 680, and they were already committed to a property before comparing the longer-term economics of different financing structures.
What ARETE would examine
Credit readiness, down-payment strategy, mortgage insurance, expected holding period, and the relationship between today's loan and the buyers' future homeownership plans—before an offer creates a deadline.